

Homeowners With Low-Rate Mortgages Should Compare the 4 Ways to Access Their Home Equity
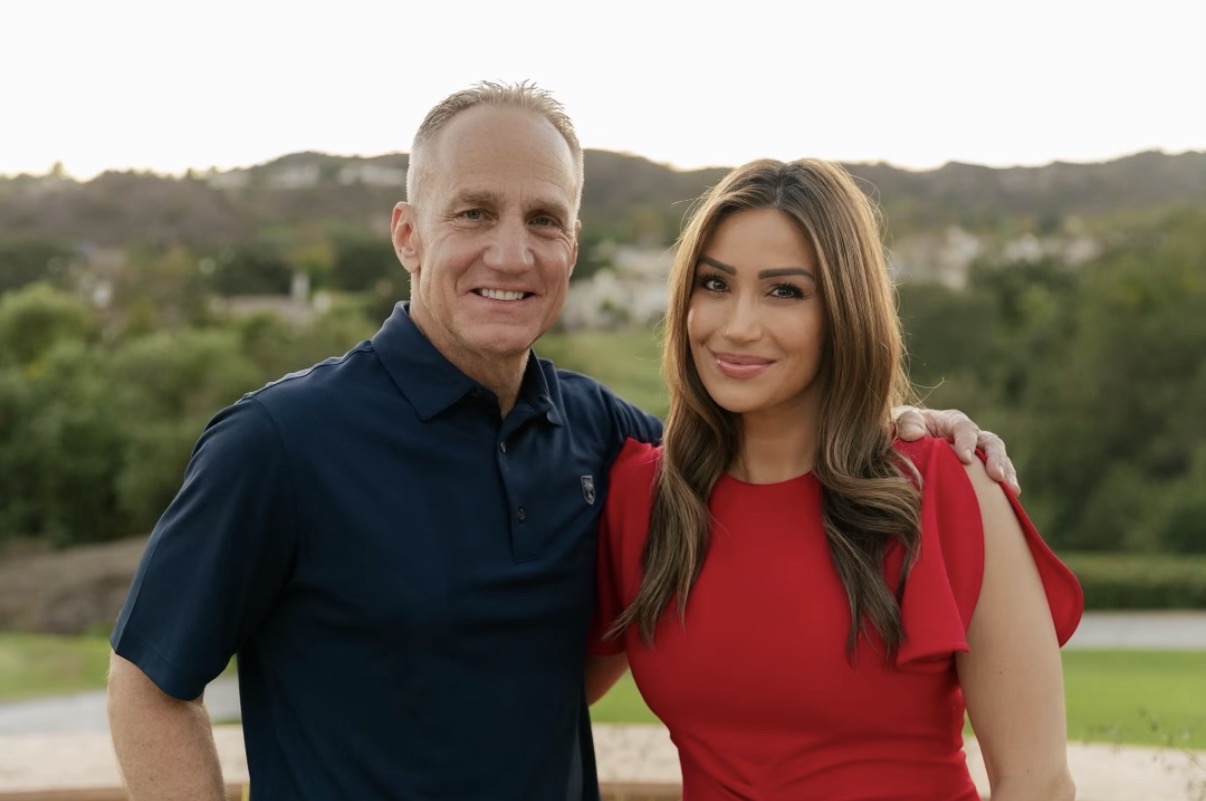
Paul and Sarah Scheper, Father Daughter Dream Team
Compare Things Apple to Apple
Run the Numbers
BBB Accredited A+ Rated
Educational guide examines HELOCs, home equity loans, reverse 2nd mortgages, and home equity investments as alternatives to refinancing low-rate mortgages.
ORANGE COUNTY, CA, UNITED STATES, October 13, 2026 /EINPresswire.com/ -- Millions of American homeowners who purchased or refinanced their homes between 2019 and 2023 may have a significant financing advantage: a first mortgage with an interest rate below 4.50%.
With current mortgage rates much higher than the rates attached to those existing loans, replacing a low-rate mortgage through a traditional cash-out refinance is no longer a prudent financial move.
"That low-interest mortgage can be a valuable financing advantage, particularly when the cost of new borrowing is significantly higher," says Paul E. Scheper, CRMP, CSA, MBA, a California mortgage professional licensed since 1984. "Before replacing a favorable first mortgage to access cash, homeowners should understand the alternatives and compare the the 4 best options to access home equity."
Scheper recommends that homeowners explore four potential ways to access home equity while retaining their existing first mortgage: a home equity line of credit, a traditional home equity loan, a reverse second mortgage for eligible borrowers, and a home equity investment.
Each option has different qualification requirements, repayment structures, costs, and long-term consequences. The most appropriate solution depends on the homeowner's financial circumstances, available equity, and future plans.
A SIMPLE $100,000 EXAMPLE
Consider a homeowner with the following financial picture:
Current home value: $1,000,000
Existing first mortgage: $200,000 at 3% interest
Estimated home equity: $800,000, before selling costs and other potential obligations
Additional cash needed: $100,000
Assumed annual home appreciation: 1.5%
The objective is straightforward: obtain $100,000 without replacing a below-market fixed first mortgage.
Rather than assuming a cash-out refinance is the best solution, Scheper recommends evaluating four alternatives and comparing their total costs, payment obligations, and potential impact on future equity. "Because my company is approved to offer all 4 options, it's important to look at all four option to weigh the pros and cons," says Scheper, President of Loangevity Mortgage based in Orange County, CA.
PLAN A: HOME EQUITY LINE OF CREDIT (HELOC)
A home equity line of credit is often a logical first option to explore.
A HELOC allows homeowners to borrow against available equity through a revolving credit line while retaining their existing first mortgage. Interest is generally charged on the amount borrowed, rather than the entire credit limit.
Many HELOCs have variable interest rates, although terms vary by lender. Monthly payments are typically required, and payment amounts may change as rates or repayment terms change.
Qualification generally depends on factors such as credit history, income, existing debt obligations, available equity, and the ability to repay.
For homeowners who qualify and can comfortably manage the payments, a HELOC may provide a flexible way to access funds without disturbing a low-rate first mortgage.
However, homeowners should review the interest rate, fees, draw period, repayment period, and potential payment increases before committing.
PLAN B: HOME EQUITY LOAN (HELOAN)
A traditional home equity loan provides another way to access home equity while keeping the existing first mortgage in place.
Unlike a revolving HELOC, a home equity loan typically provides a lump sum with a fixed interest rate and scheduled payments over an agreed term.
Qualification generally requires acceptable credit, verifiable income, sufficient equity, and the ability to manage the additional debt.
For homeowners who can afford the payments, a home equity loan may offer predictable borrowing costs and a defined repayment schedule.
Both HELOCs and home equity loans should be evaluated carefully. Their overall cost depends on the interest rate, fees, repayment period, and how quickly the homeowner intends to repay the borrowed funds. The rates for these two programs are lower, but proving stellar credit, strong income and solid assets is not always easy.
Regular principal and interest repayment can help reduce the outstanding balance over time, although interest and fees affect the total cost.
But what happens when a homeowner cannot qualify for traditional financing or cannot comfortably afford another required monthly payment?
That is when the next two alternatives may warrant consideration.
These last two options carry a higher interest rate, but allow the monthly payments to be deferred (to be paid later).
PLAN C: REVERSE SECOND MORTGAGE — ACCESSING EQUITY WITHOUT REQUIRED MONTHLY PRINCIPAL-AND-INTEREST PAYMENTS ON THE NEW LOAN
For eligible older homeowners, a conventional reverse second (2nd) mortgage may provide access to home equity without requiring monthly principal-and-interest payments on the new second mortgage. Payments are optional -- they can be paid voluntarily (to keep the loan amount lower), or they can be accrued and added to a rising loan balance.
The homeowner retains the existing first mortgage and continues making its required payments. The reverse second mortgage is a separate obligation secured by the property. "Simply put -- the monthly payment on this type of loan is paid from the homeowner's equity, instead of their checking account," according to Scheper.
Depending on the specific program, eligibility may begin at age 55. Age requirements and other qualifications vary by lender and product. As mentioned, an important consideration is that interest and applicable fees on a reverse second mortgage can accumulate over time, increasing the outstanding balance. The loan must eventually be repaid according to its contractual terms.
Homeowners must also continue meeting their obligations under the existing first mortgage and remain current on property taxes, homeowners insurance, applicable HOA assessments, and property maintenance requirements.
Unlike an equity-sharing agreement, a reverse second mortgage is a loan rather than a contractual exchange of a share of future appreciation. The homeowner generally retains full control of the property's future appreciation, subject to the outstanding mortgage obligations and other costs.
For eligible homeowners (Age 55+) who need cash but want to avoid adding another required monthly principal-and-interest payment, this option may be worth comparing with traditional financing. The absence of a required monthly principal-and-interest payment does not mean the financing is free. The interest rate, fees, repayment triggers, and projected loan balance should all be evaluated before proceeding.
PLAN D: HOME EQUITY INVESTMENT (HEI) — CASH TODAY IN EXCHANGE FOR A FUTURE SETTLEMENT
A home equity investment offers a different approach for homeowners seeking access to equity without taking on a traditional loan with required monthly payments. This program is surging in popularity right now, because sometimes, credit scores as low as 500 are acceptable, and there is often no verification of income or assets.
An HEI is generally structured as a contractual equity-sharing agreement. The homeowner receives cash today and agrees to make a future settlement payment determined by the agreement's terms, often in connection with a sale, refinance, or other specified settlement event.
Depending on the provider and agreement, qualification may place different emphasis on income, credit, and available equity than a traditional home equity loan. However, HEIs are not universally available to homeowners with credit or income challenges.
The key trade-off is the potential future cost. Depending on the contract and changes in property value, the settlement obligation can increase substantially. Fees, valuation adjustments, minimum-return provisions, and other contractual terms may also affect the amount ultimately owed. The homeowner generally retains legal title to the property, but commits a portion of its future economic value to the HEI provider under the agreement.
Unlike a traditional loan, an HEI does not necessarily charge interest in the conventional sense. Instead, the provider's return is calculated according to the contractual formula. This can make direct comparisons with mortgage interest rates misleading, so it's important to compare side-by-side amortization charts (yearly) to see "what will be owing year by year."
An HEI may be appropriate in certain circumstances (especially when the first three plans do not pencil). Homeowners should carefully review the agreement, understand how the settlement amount is calculated, and examine how different appreciation scenarios would affect the final obligation. They should also consider whether they could afford to settle the agreement without selling the home if required.
In some situations, an HEI may compare favorably with a reverse second mortgage. In others, the long-term cost of sharing future appreciation may be greater than the cost of borrowing. A side-by-side analysis using the actual contract terms is essential.
EVEN 1.5% ANNUAL HOME APPRECIATION CAN MAKE A DIFFERENCE
Using the $1 million home example, the following illustrates how a modest assumed annual appreciation rate of 1.5% could affect the property's value.
Today: $1,000,000
5 years: $1,077,284
10 years: $1,160,541
15 years: $1,250,232
These projections assume 1.5% annual compound appreciation, with no adjustments for market fluctuations, property improvements, or selling costs. Actual property values may increase or decrease.
After 15 years, the property would be worth approximately $250,000 more under this hypothetical scenario.
However, appreciation alone does not determine how much equity the homeowner ultimately retains. The outstanding balance on the existing first mortgage, any additional loan balances, accrued interest, fees, and the contractual terms of an equity-sharing agreement all affect the outcome.
For a HELOC or home equity loan, the balance depends on the amount borrowed, interest rate, fees, and payments made.
For a reverse second mortgage, the balance may grow over time if interest and fees accrue without monthly principal-and-interest payments.
For an HEI, the settlement amount depends on the agreement's specific formula and the property's value at settlement. These differences make it important to compare the actual projected obligations rather than relying solely on an advertised rate or the absence of monthly payments.
FOUR PLANS. ONE IMPORTANT DECISION.
Scheper recommends evaluating each option based on the homeowner's ability to qualify, affordability, immediate cash needs, and long-term financial objectives.
Plan A — HELOC: Consider a revolving credit line when flexibility is important and the homeowner can manage the required payments.
Plan B — Home Equity Loan: Consider a lump-sum loan with a predictable repayment schedule when the additional monthly payments are affordable.
Plan C — Reverse Second Mortgage: For eligible older homeowners (Age 55+), evaluate a loan that may defer required monthly principal-and-interest payments on the new loan while allowing the homeowner to retain ownership and future appreciation.
Plan D — Home Equity Investment: Consider an equity-sharing agreement when the first 3 plans are examined and do not seem suitable. This plan is very easy to qualify for because of relaxed credit and income requirements, but it's important to know what you will owe in 5, 10, 15 or 20 years. The term of this plan typically matches the term of the existing 1st Mortgage, which will remain on the home.
"Plans A and B are often sensible starting points for homeowners who qualify and can comfortably afford the payments," Scheper explains. "But if traditional financing isn't feasible, or another monthly payment would create financial hardship, it is worth understanding the other two alternatives." He emphasizes that no single solution is right for everyone. The appropriate choice depends on the homeowner's age, financial resources, existing mortgage, credit profile, anticipated length of homeownership, and willingness to accept future obligations.
IT PAYS TO KNOW. IT PAYS TO COMPARE.
With more than four decades in mortgage lending, Scheper believes homeowners benefit from understanding multiple financing alternatives before making a decision that could affect their finances for years.
"The most important thing isn't which program sounds best in an advertisement. It's which option makes the most sense for your circumstances, both today and 5, 10 or 15 years from now," Scheper says. "Before you sign any agreement that commits future equity or take on a loan that accumulates interest, compare the costs and obligations side by side," concludes Scheper.
ABOUT LOANGEVITY MORTGAGE
Loangevity Mortgage helps homeowners explore and compare mortgage financing strategies, including traditional mortgages, home equity lines of credit, home equity loans, reverse mortgage alternatives, and home equity investment agreements.
Led by Paul E. Scheper, CRMP, CSA, MBA, a mortgage professional licensed since 1984, Loangevity Mortgage emphasizes consumer education and informed decision-making. The company helps homeowners understand the potential benefits, costs, and trade-offs of different financing options so they can make decisions aligned with their financial goals.
Holly Hackett, Media and BBB Liaison
Loangevity Mortgage
+1 800-662-6784
Visit us on social media:
LinkedIn
Instagram
Facebook
YouTube
X
Legal Disclaimer:
EIN Presswire provides this news content "as is" without warranty of any kind. We do not accept any responsibility or liability for the accuracy, content, images, videos, licenses, completeness, legality, or reliability of the information contained in this article. If you have any complaints or copyright issues related to this article, kindly contact the author above.
